Showing posts with label 2008 Financial Crisis. Show all posts

Friday, March 14, 2014

J.P. Morgan: Strategic Shifts Amidst Changing Consumer Behavior

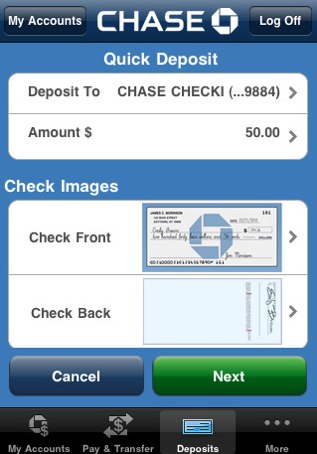
Chase Mobile Banking Application


Today, J.P. Morgan & Chase updated its forecast regarding employment cuts, announcing expected reductions of 8,000 jobs from its mortgage operations and retail branches over the course of 2014. These cuts are over 2,000 more than original projections.Furthermore , this employment reduction is on top of the 16,500 cuts made last year by the U.S. banking giant. 

However, total employment will be reduced by only 5,000 jobs due to the addition of 3,000 new jobs to the bank's compliance department. Compliance departments of major banks have become increasingly crucial since the '07-'08 global financial crisis. J.P. Morgan has agreed to over twenty billion dollars in settlements over just the past year, with other federal probes waiting in the wings. However, it is an acknowledged reality that demand for compliance expertise currently exceeds the pool of qualified personal, suggesting that money, and perhaps jobs, will be shifting gradually toward that area.

Legal issues aside, a great deal of J.P. Morgan’s strategic shift can be attributed to changing consumer behavior amidst advents in consumer banking technology. In addition to the employment cuts the bank also announced today that it would be curbing the expansion of its branch network. Over the past three years, J.P. Morgan added 360 new physical locations. However, customers’ growing reliance on paperless banking and automated teller machines has undercut the utility of the once essential brick-and-mortar banking stations. Moreover, the recent spike in online banking, namely the ability to cash checks through photos on encrypted mobile applications, has reduced demand for representatives and teller transactions.
--
Arthur Gosnell

Friday, November 15, 2013

Book Review: Too Big to Fail

Too Big to Fail: The Inside Story of How Wall Street and Washington Fought to Save the Financial System and Themselves
By Andrew Ross Sorkin

“The Most important risk is systematic: if this dynamic continues unabated, the result would be a greater probability of widespread insolvencies, severe and protracted damage to the financial system and, ultimately, to the economy as a whole” -- Timothy Geithner

The quotation above by Timothy Geithner, then head of the New York branch of the Federal Reserve in 2008, strikes at the heart of the finical crisis of 2008 and the severe consequences it posed for our nation’s economy. The economic recession that struck the global financial system was a historic and unparalleled crisis that challenged the bedrock of modern finance. It was a global recession that hit not only the United States but also every country that was exposed to the global banking system, a now essential and interconnected element of every developed economic nation. Dubbed by Ben Bernanke, Chairman of the United States Federal Reserve, as the worst economy since the great depression, the economic downturn in 2008 had far reaching and lasting effects that resulted in stunning losses not only on Wall Street, but Main Street as well. As an academic, and student of the Great Depression of the 1930’s, Bernanke was well aware of the stunning similarities between the then current declining situation and the era that crumpled the country for a decade. The turmoil of 2008 facilitated marked changes across the financial as well as governmental systems that would forever alter the business landscape within America.

Sorkin’s “Too Big to Fail” is an expertly written chronicle of the 2008 financial crisis: in particular the institutions and individuals who had leading roles in both its downfall as well as salvation. The book is above all a chronicle of human folly and the incredible mistakes made not only within this short window of 2008, but throughout the past 30 years of American business. The first and most essential aspect of understanding this book; and an element which Sorkin does well to point out; is how the crisis was not created or caused by events in 2008, but was the culmination and synthesis of a myriad of different factors that had been created for the better part of three decades. If one can learn anything form this book it is that there is no one element, no one smoking-gunthat can be attributed to the crisis of 2008; but a combination of complex and interconnected factors. The unprecedented growth or boomof the US economic system during the 80’s & 90’s laid the foundation for much of the 2008 recession. The US economy was on the rise, credit was flowing and mortgage industry was seeing incredible growth. With governmental pressure to promote homeownership and relaxed lending standards, the home mortgage industry was steering itself into a massive hole. No where was this rise to profitability more prevalent than within the financial services industry, by 2008 it has ballooned to more than 40% of corporate profits in the United States. (Sorkin, p. 3) It was a Wealth-creation machine known for large salaries and even larger risks. This rise is what marks the beginning of the many interrelated themes Sorkin highlights within the book.

The key characteristic of Sorkin’s book, a compilation of interviews and research, is that is flows chronologically; starting with the collapse and eventual sale of Bear Stearns to JP Morgan in March of 2008 all the way to the enactment of the government’s TARP (Troubled Assets Relief Program) in October. Although it was difficult at times to understand the multitude of events occurring so quickly and simultaneously; this calculated decision by Sorkin was critical to demonstrating the overwhelming nature of the period. The individuals facing these challenges were met with an ever-shifting landscape that would change daily if not hourly; their decisions were imperfect, but how could they not be -- they were simply doing the best they could during a terrible situation. As for the content of the book; it explains the rise and then fall of the interconnected banking system though the eyes of the people living through the crisis. The book highlights the complex financial instruments, risky lending practices, risk consolidation, leverage, asymmetric information as well as the many other factors that lead to the crash; however, Sorkin goes beyond simple description and does his best to distinguish to broader stokes of the crisis by placing it within the larger context of human decision making. Such terms as moral hazard and irrational exuberance are used to describe the key drivers of human error that lead to economy astray. (p. 33) For in the end, it was not financial products or lending standards that lead to the crisis of 2008, its was individual’s misguided decision making to use these complex instruments or sign off on a risky loan that truly lies at the heart of the crisis. The economy was not an autonomous decision maker; it was individuals who shepherded it into failure. The most important dynamic explored within Too Big to Fail, was the role of the government within these uncertain times, and its responsibility to protect the financial system. Never before in history had the government’s regulatory agencies played such an important and active role within the American economy. The fundamental characteristics of capitalism and a free market economy were severely challenged; some financial institutions had become so large and so integral to the rest of the system that letting them fail was simply not an option. What had started on Wall Street had become an epidemic of confidence all across the economy. This loss of confidence within the financial system is one of the few week points in the book; Sorkin does not fully explain the paralyzing consequences that a loss of confidence had on the system. The economy is not simply a machine that runs on tangible assets, it’s a larger symbiotic organism that relies on the hypothetical and theoretical relationships created by a collective trust in the system. Perception became the reality, and the economy stumbled. This relationship between Wall Street and Washington; and the interplay between the parties has forever shaped our nation. While many books have been written about the crisis, its origins and its ramifications; no other book offers such substantive insight into this brief period of time that will continue to guide the US economic system. Sorkin recreated the twelve months of 2008 that will most likely shape the economies path for the next twenty years. The crisis shook free many of the false realities our nation had about wealth creation and forced us to take a harsh self-evaluation of who we are as a country and what choices we are making. It pushed us to face the uncomfortable reality that we have serious challenges ahead of us, and that we can no longer afford to live blissfully unaware to the consequences of our actions. Our nations’ fanatical drive towards material wealth must come to an end; the 2008 crisis is evidence of that.

Too Big To Fail, is a delightful read that presents the details of the crisis in a manageable and tangible manner. But by far its strongest quality was its ability to truly create the individuals who had to face these epic challenges and make decisions that would impact not only the United States, but also the world at large. It truly is an illumination of human discourse, reasoning, ineptitude and brilliance; and how the leaders of the financial system coped with the potential destruction of our economy and how they lead their companies and the nation to a more stable place. The book constructed a window into the past for us to understand how the decisions were made and where adversities arose. I became intimately connected to the characters and the firms; griped by the books consistent flow and steady stream of relevant information. Sorkin does a wonderful job of constructing the larger contextual framework in which these decisions were made. It presents the reader with meaningful questions and timely opportunities to evaluate what they have read and what it means to them within everyday life. Well written and gripping, I would recommend this book to anyone interested in finance, as well as to anyone engrossed with the future of our nation and our economic system. Sorkin does not harp upon financial instruments or paint a morbid picture of egotistical bankers running wild; but fairly presents the crisis in a context that is significant to any reader, i.e. ‘where do we go from here’?
--
Editorial Staff 

Sunday, January 15, 2012

Book Review: The Big Short

The Big Short 
By Michael Lewis 

The world of finance is one of losers and winners. When the sub-prime mortgage crisis hit the market in 2007, the big Wall Street firms with huge pile of sub-prime mortgage bonds lost while a few wise men betting against these bonds won. In Michael Lewis’ Book The Big Short, Lewis recounts the story of how a handful of Wall Street misfits anticipated the doom of the sub-prime mortgage bonds and made a fortune betting against the home-price inflation in mid-2000s. Lewis successfully tells the story with humor and clarity, considering the complexity of the sub-prime mortgage bond market before the crisis. However, his account of the financial crisis in 2007 is biased in that it exaggerates the effects of the public feature of investment banks, ignores factors such as government’s policies that lowered borrowing standards and neglects home owners’ speculative behavior.

Lewis overstates the effects of the public nature of the major investment banks. Lewis points out, toward the end of his book, that what lied at heart of the crisis was that all the major investment banks went public rather than functioned as partnerships. (Lewis traced the crisis back to a decision John Gutfreund had made- when he’d turned Salomon Brothers from a private partnership into Wall Street’s first public corporation.) Here is his logic: if a major investment bank were organized like partnership, each partner would have been more careful with their decisions and taken fewer risks. Now that these banks were public and the bankers were operating with shareholders’ money, they had few incentives to scrutinize their decisions or products because they could transfer risks to their shareholders; that was what led these firms to use high leverage and buy a great amount of sub-prime mortgages bonds without even knowing what were underlying these assets. (Lewis, 257) Lewis states that the incentives on these public Wall Street firms are entirely wrong because the bankers can get rich [even] when they are making dumb decisions. (Lewis, 256) In short, Lewis is saying that people within the investment banks took excessive risks because they had nothing to lose. This statement is not sound. First, the bankers did have many things to lose. Many individuals most responsible for the massive money loss during 2005-07 were the largest shareholders in their companies. These individuals lost money when their firms suffered.

In other words, they did not transfer much risk to the companies’ shareholders. Even though Howie Hubler, a former trader at Morgan Stanley, got away with large bonuses, the majority of the Wall Street professionals responsible for the crisis suffered from the crisis. Jimmy Cayne (CEO of Bear Stern)’s stock declined from 1 billion to 50 million. Richard Fuld (Lehman’s chairman) lost 550 million of his Lehman stocks when Lehman Brothers went under. The bankers had a great deal of interest within these firms. These individuals did want their firms to perform well. Even though the bankers are employees in a public company, they are effectively like partners in a partnership company because of their large stock holdings. Therefore, the employees engaged in careless behaviors not because they were in a public firm, but rather, because of some other factors. Second, we can refute the author’s contra-positive statement: if an investment bank were not public, bankers would not have been as careless. To refute this, just imagine that an investment bank were actually a partnership. In this case, a banker would still have bought those mortgage bonds because they were led to believe that they could make profits in these bonds. The only difference would be that the bank would not have had the ability to raise funds in the stock market. In this case, these partnership firms would just have found other creative ways to raise enough capital to buy the mortgage bonds, which would eventually lead to the 2007 crisis. To conclude, the mere fact that the major investment banks were public is not important in causing the crisis.

Moreover, the book is biased in that it gives all the blame to investment banks and ignores the government’s policies’ effects on the crisis. If the government did not lower the borrowing standards and encouraged lending at Fannie Mae and Freddie Mac, the crisis might never have had happened. Here is what happened: at first, the banks were making money with bundling mortgages backed securities backed with good credit and down payment and selling them to investors. Then they became greedy and wanted to make more money by making more loans. When there were not enough people with good credit, the banks invented credit default swaps. (In the book, a trader named Mike Edman within Morgan Stanley came up with this idea). With these swaps, a bank could give out loans to people with low credit score and little down payment. However, a loan could be granted only if it fulfilled the underwriting standards designed by the government. Therefore, the banks had to persuade the politicians to ease the underwriting standards. The investment banks then spent huge amount of money to get the government ease the standards. Then Barney Frank was saying that everyone deserves to own a home and Bush was saying that everyone deserves to live the American Dream. Clearly, if the government had not relaxed lending standards, the investment banks would have never got the chance to create the CDOs, which eventually led to massive defaults of people who should not have owned houses at first place. True, the investment banks were greedy. However, without the help of the government, they would have never been able to unleash their greed. The book also ignored that homeowner speculation also contributed to the crisis. In the book, the homeowners who got sub-prime loans were depicted as poor people who were told by the mortgage sellers to tell lies and who got deceived by the teaser rate and was later ripped off by the real rate. (Lewis, 19) These customers were truly the victims of the entire housing market scheme.

However, we had another crowd of customers who had more than one house, to whom we should not be as sympathetic. They were buying houses as speculative investments. During 2006, 22% of homes purchased were for investment purpose, with an additional 14% purchased as vacation homes. During 2005, these figures were 28% and 12%, respectively. The widespread speculation pushed house prices up dramatically. Housing prices nearly doubled between 2000 and 2006. Many homes were purchased even when they were still under construction and then sold for a profit without the sellers ever having lived in them. The housing bubble was so big that Warren Buffett stated that it was the greatest bubble he has ever seen in his life. The question is how did the broad speculation contribute to the crisis? The rising housing price gave mortgage sellers excuses to give out sub-prime mortgages, whose defaults eventually led to the crash. The inflating house prices also gave credit to the CDOs that investment banks created and encouraged large trading volume of CDOs, which increased the magnitude of the crash. As a reader, it is hard not to wonder how could Lewis know every time in advance that a crash was coming and went about documenting it, as what he did when he wrote Liar’s Poker and this book. It must be that the crash had shown its signs in times of prosperity and Lewis captured these signs.

We should learn to be as forward-seeing as Lewis is. We are just four years away from when the crash happened and our economy is still not fully recovered. As we gradually pull ourselves out of recession, let’s remember the lessons learned in the past and walk with great care. And here, we refer not only to investment banks, but also the government and every average American citizen.
--
Editorial Staff

Monday, November 14, 2011

Market Recap (Nov. 14)

After opening the week strong, the Dow Jones Industrial Average (DJIA) sustained severe losses at the opening bell on Wednesday, finishing the day down 3.2%. This overnight drop was caused predominantly by the news that Italy’s borrowing costs would continue to rise. Investors acted on concerns about the credit status of Italy and instability in the Eurozone in general. The market bounced back on Friday as plans for an interim government after the imminent resignation of Prime Minister Silvio Berlusconi began to emerge. As expected, Berlusconi resigned on Saturday as the lower chamber of Italy’s parliament approved new austerity measures in a revised budget bill. Mario Monti, an economist and former European commissioner, was announced as Berlusconi’s successor effective Sunday night. Investors will likely react favorably to this decision by parliament given the extremely negative perception that the international community at large held with respect to Berlusconi’s leadership.

Europe’s debt crisis remains one of the most significant roadblocks to sustainable increases in the markets. On the whole, the economy is slowly recovering as is reflected in generally fair valuations and better-than-expected quarterly earnings reports. Eurostat will release reports on industrial production and inflation within the Eurozone on November 14 and November 16 respectively. These reports will provide important insight into the overall economic health of the countries that investors have been so focused on. Investors are also worried about the increasing spreads in yield premiums between Germany and other large Eurozone countries such as France, Austria, and Belgium. If these spreads do not tighten over the next week, the market will likely fall off the gains it made late this past week.

Earnings reports from Walt Disney Corp. (DIS +0.95%) were released this week. Disney announced a rise in fourth-quarter earnings Thursday afternoon, giving investors a pleasant surprise. Bond markets were closed for Veteran’s Day on Friday but positive developments over the weekend in Europe (specifically in Italy) should promulgate a bond selloff on Monday that could push equities even higher. Of course, this increase will likely not be sustainable unless regulators can come up with a viable plan to keep Italy’s and other struggling countries’ borrowing costs low.
--
Editorial Staff